


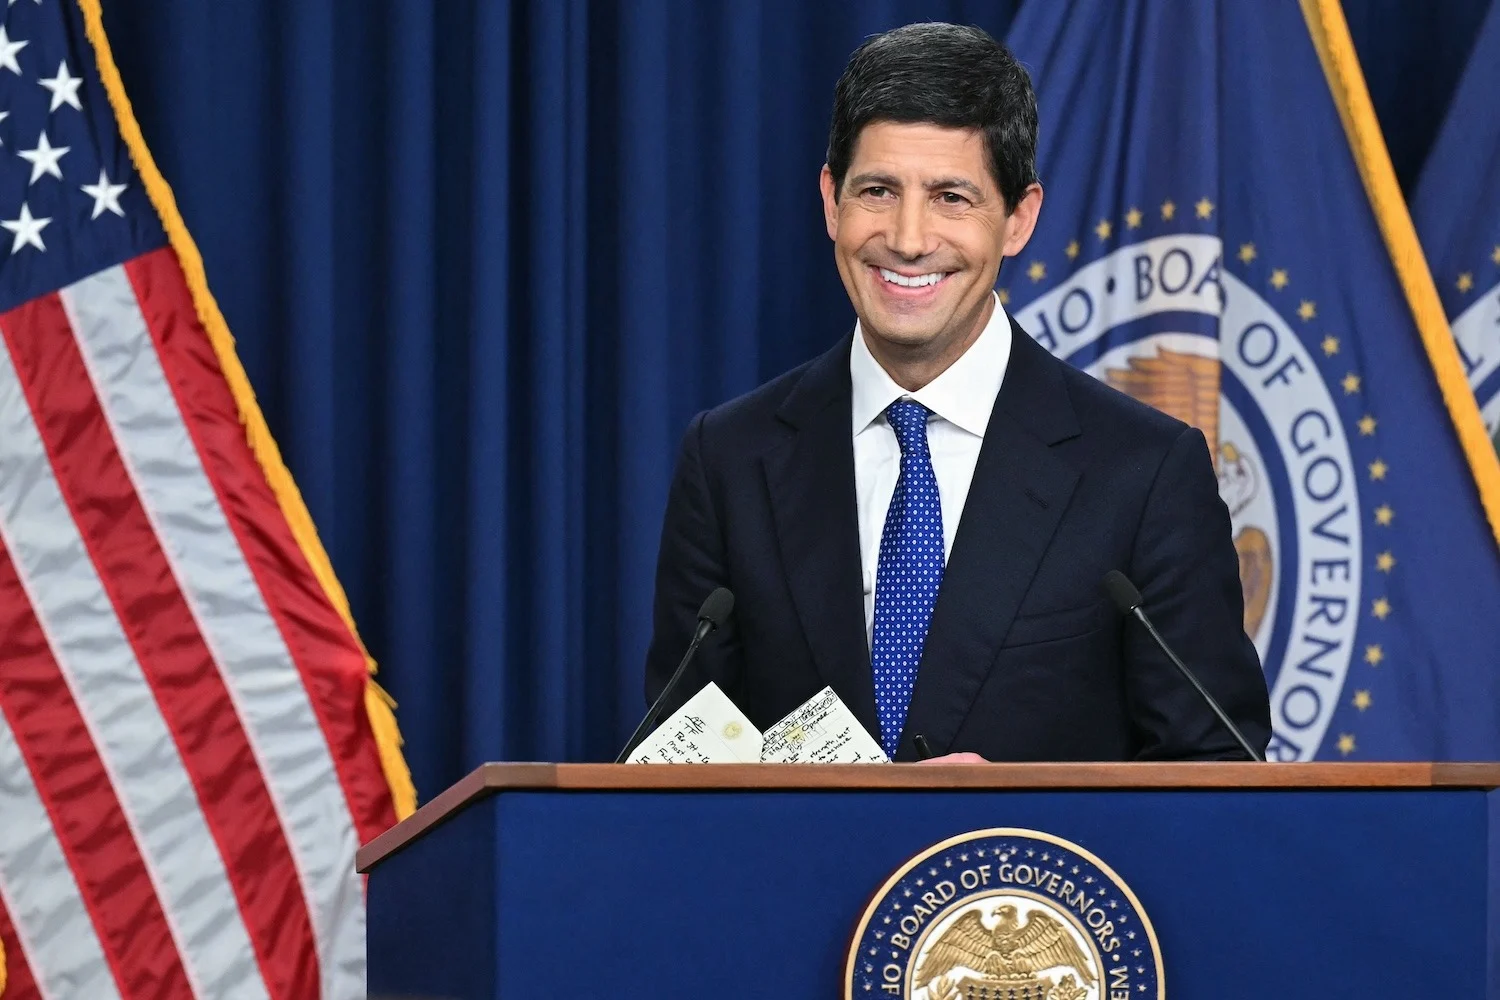
Kevin Warsh, the man U.S. President Donald Trump tapped to lower interest rates, on Wednesday presided over a unanimous decision to hike U.S. borrowing costs for the first time in three years due to concern over rising inflation.
Most officials at the U.S. Federal Reserve also signaled that rates are likely to keep creeping upward, with at least one more rate hike later this year and more to follow in 2027.
Kevin Warsh, the man U.S. President Donald Trump tapped to lower interest rates, on Wednesday presided over a unanimous decision to hike U.S. borrowing costs for the first time in three years due to concern over rising inflation.
Most officials at the U.S. Federal Reserve also signaled that rates are likely to keep creeping upward, with at least one more rate hike later this year and more to follow in 2027.
“The plain fact is that inflation is too high and has been for too long,” Warsh, who assumed the role of Fed chair in May, said at a press conference after the Wednesday meeting.
The decision to raise interest rates by one-quarter point was widely anticipated by markets in the wake of Warsh’s speech last month at a major conference; anything less than a modest rate hike would have unleashed a brutal response from investors. Yet Warsh may still face a nasty rebuke from Trump, who has demanded lower rates to kick-start the economy.
But the decision is a reflection that the ongoing costs of the war in Iran, as well as Trump’s trade wars, are carrying real consequences for a U.S. economy already strained by mounting debt and unchecked fiscal profligacy.
Warsh highlighted “geopolitics” as one of the things that had changed since the Fed held rates steady in its last meeting. “There’s no hiding from hot spots around the world,” he said.
Warsh, who has struggled to convince investors and global markets with his spare communication style that he understands the traditional role of the Fed to be a reliable thermostat for the global economy, again refused to offer much guidance on future decisions, other than to reiterate that “this committee will deliver price stability,” which hints at higher interest rates (for mortgages, for car loans, for business loans) for the next year at least.
U.S. markets took the decision and Warsh’s words in stride, with little change in already-high bond yields and only a small and expected dip in stock markets.
The stage had already been set for the first rate hike in three years when inflation data from August came in higher than expected (a 3.4 percent annual clip), dispelling the last hope that slightly moderating inflation earlier in the summer meant the Fed was inching closer to its target of 2 percent inflation.
Fed Gov. Christopher Waller, who had voted to hold interest rates steady at the July meeting, flagged as much in a speech this month. “If the incoming data for August show this improvement has been fleeting, then it may be appropriate to raise the policy rate,” he said. Inflation, he stressed, was the key factor in this month’s Fed meeting because other aspects of the economy, including jobs, employment, and overall growth, remain solid and mitigate against any move to start hiking interest rates.
But that August uptick in prices led market observers overwhelmingly to expect the Fed to raise rates, even though some economists (and for a period this summer, Warsh himself) argued that the market had already essentially raised borrowing costs by driving up the yields on long-term U.S. debt to 20-year highs, making further action by the Fed less necessary.
Those bond-market woes, though not unusual in historic terms, are a departure from recent U.S. experience and a direct result of runaway debt and deficits, unchecked issues of fresh debt, and a growing wariness among even friendly countries about continuing to prop up the U.S. dollar as the keystone of the world financial system.
The drivers of the stubborn inflation include energy prices, which are rising rapidly because of the ongoing war in Iran; the continued impact of U.S. tariffs; and price pressures stemming from the huge investment in artificial intelligence. The Producer Price Index ticked higher in August as companies paid more for their inputs.
Energy prices may be most problematic for consumers and policymakers in the months ahead due to the expanding war in Iran. Crude oil prices have jumped to well over $100 a barrel as the Iran-backed Houthi rebels in Yemen have begun interfering with the other crucial waterway through which energy flows. (The Houthis have stepped up their attacks in the Bab el-Mandeb this week, and Saudi Arabia is curtailing shipments of oil to Europe for the next few months after a disruption to its main East-West pipeline.)
That has led to a sharp increase in the price of gasoline and diesel for U.S. drivers, with diesel in particular at record highs of more than $6.30 a gallon nationwide. Costly diesel has a big knock-on effect on the rest of the economy because it fuels the trucks, tractors, and trains that make and move so many products. The U.S. Congressional Budget Office just concluded that the Iran war, and particularly its impact on energy, will lead to continued higher inflation into the beginning of 2027.
That’s one reason why markets expect the Fed to raise rates at least twice more over the next year, and perhaps more, in a bid to get inflation under control. The intent (and downside) of increasing rates is that they raise the cost of borrowing, which acts as a drag on investment and consumption and so can slow down economic growth (and inflation).
One problem, and it’s a big one, is that Fed rate decisions can do little to ameliorate inflation that comes from external shocks, such as a historic energy crisis. (Fed decisions are better at curbing loose-money inflationary bubbles.) Warsh acknowledged as much on Wednesday, but he said a “less accommodative” monetary policy could at least limit higher energy prices from bleeding through the broader economy.
That’s a major reason why the Trump administration has continued to pressure Warsh not to raise rates, even as inflation inched upwards and many officials broached the idea of rate hikes. Trump, who has long demanded lower interest rates and targeted former Fed Chair Jerome Powell over his refusal to cut rates, even mulled the idea of additional tariffs if the U.S. central bank didn’t do his bidding.
White House economic advisor Kevin Hassett warned Warsh not to raise interest rates ahead of the U.S. midterm elections, arguing that such a move might be seen as political and damage the central bank’s independence. But holding steady just before the elections and bowing to the White House, despite some worrisome economic data, would have been even more damaging to the Fed’s independence.
Warsh maintained much of his Delphic style in Wednesday’s press conference and refused to speak of any White House threats, apparently navigating a Scylla and Charybdis of pressure from multiple directions.
“Price stability is fundamental to economic growth,” Warsh said but added, “I’m not going to prejudge any future decisions we make.”
