


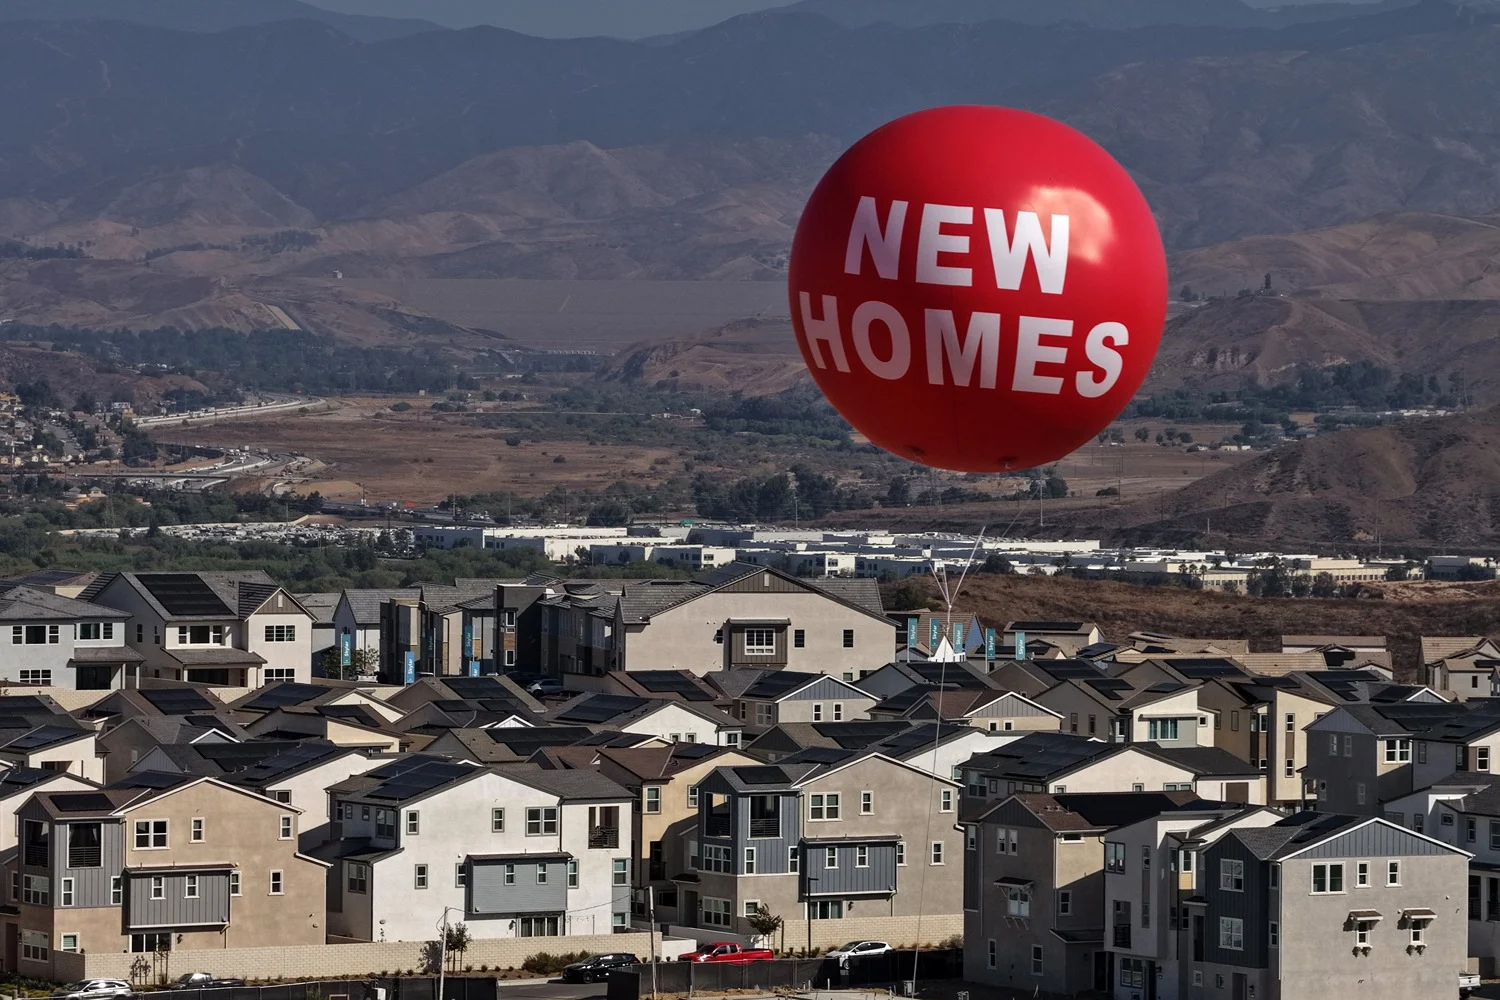
The annual rate of home sales in the United States recently fell to 3.98 million, its lowest level since June 2025. The stagnant housing market may be because of the country’s elevated interest rates, with the average 30-year fixed mortgage rate now past 7 percent. That makes it more than just a housing story, because the interest rate is partly determined by competition for capital from the booming artificial intelligence industry.
What are the dynamics in play in the U.S. housing market right now? Are high U.S. interest rates mostly due to broad economic growth? What role is the AI industry playing in the frozen housing market?
Those are just a few of the questions that came up in my recent conversation with FP economics columnist Adam Tooze on the podcast we co-host, Ones and Tooze. What follows is an excerpt, edited for length and clarity. For the full conversation, look for Ones and Tooze wherever you get your podcasts. And check out Adam’s Substack newsletter.
Cameron Abadi: What exactly is going on in the housing market? How would you describe the dynamics at play right now?
Adam Tooze: The term that seems to be commonly used by analysts is “freezing up” or “frozen.” The mortgage rate is over 7 percent, which is lower than the 7.7 percent rate in 2023 when inflation spiked. But the crucial point is that as recently as 2022, you could get a mortgage for as little as 3 percent; during COVID, it fell even lower than that.
An increase in interest rates from 3 percent to over 7 percent is a huge financing shock to what is the largest single asset class in the world. By comparison, U.S. Treasurys is a $40 trillion asset pool; American domestic real estate, so housing, is $55 trillion, of which owner-occupied is $48.7 trillion. This is flat-out the single largest element of the U.S. economy. If you add in commercial real estate, it’s $26 trillion.
For the financing costs on a market that large to shift as much as this is a story that ought to rank alongside the Treasurys in terms of its macroeconomic implications. Because it impacts households and therefore impacts consumption, it in some senses is a more direct impact on people’s lives.
Another way of describing this is that this is another aspect of the cost-of-living crisis and conversation going on in American society, as it has in so many others in recent years. It’s also a K-shaped story about the division within American society at its most elemental level—namely, what do you pay and how do you finance your home? American mortgages are very peculiar beasts by global standards. They offer fixed rates for very long periods of time but with the one-sided advantage to the borrower that they can refinance whenever they like, essentially, for relatively modest cost and it’s a normal thing to do.
So what happens is that when interest rates fall, people who are well-organized financially refinance their mortgages. Currently, about 50 percent of American mortgage holders are locked in on 30-year interest rates that are less than 4 percent—incredibly good financing, given that the inflation rate in the U.S. is currently ticking along at 3 percent. Half of that population is locked in, and for them to consider moving, they would have to refinance—presumably if they’re moving up the chain—more money at a rate that is not 4 percent but 7 percent. So it’s incredibly off-putting.
But even if you had taken out a mortgage 12 months ago, over the lifetime of a 30-year mortgage your interest costs would be tens—if not hundreds—of thousands of dollars lower than they are right now.
So, you can see why from that side there is a real freezing pressure going on. What’s happening is precisely what you described: a contraction of the overall market. A market economist would say, the way this works is if demand falls, the price should fall. But the problem with the U.S. housing market right now is that structurally, if you look at household formation compared to new construction of buildings, there’s a fairly substantial deficit, so prices are remaining stuck high.
But even at those prices, not many people are actually willing to sell because of the refinancing costs when they move into a new property. The entire market is in this sort of frozen state. There were periods in the early 2000s during the real estate frenzy before the 2008 crash where house sales were running at the rate equivalent to 7 percent of households, so real considerable churn. Not all of those were properties that people lived in, but nevertheless it suggested a very large mobility.
That rate is half or less than half that currently—so we really are talking about a kind of deadlock.
Read More
-
A group of men in suits gather outdoors, facing one another in a circle-like arrangement. On the left, a blonde man in a blue suit and light blue tie looks toward a gesturing man in the center. Beside him, a curly-haired man wearing a dark suit with a red tie listens attentively. The gesturing man in the middle, wearing glasses and a gray suit with a patterned tie, speaks with his hands raised mid-explanation. Surrounding them are several other men dressed in formal dark suits and ties, observing the conversation against a backdrop of green foliage. A group of men in suits gather outdoors, facing one another in a circle-like arrangement. On the left, a blonde man in a blue suit and light blue tie looks toward a gesturing man in the center. Beside him, a curly-haired man wearing a dark suit with a red tie listens attentively. The gesturing man in the middle, wearing glasses and a gray suit with a patterned tie, speaks with his hands raised mid-explanation. Surrounding them are several other men dressed in formal dark suits and ties, observing the conversation against a backdrop of green foliage. America Can Regulate AI—and Still Win the AI Race
The history of banking and nuclear power suggests safety rules can strengthen rather than cripple U.S. industry.
-

A group of protesters stands in a plaza outdoors holding signs, with a large, grand domed building in the background and an American flag on the right. In the center, two people hold up a large black banner that reads “STOP THE AI RACE” in large white lettering with a red prohibition symbol over the letters “AI”. Surrounding them, demonstrators hold various handwritten signs with anti-AI slogans under an overcast sky. A group of protesters stands in a plaza outdoors holding signs, with a large, grand domed building in the background and an American flag on the right. In the center, two people hold up a large black banner that reads “STOP THE AI RACE” in large white lettering with a red prohibition symbol over the letters “AI”. Surrounding them, demonstrators hold various handwritten signs with anti-AI slogans under an overcast sky. Can AI Be Regulated?
Frontier AI labs are calling for government oversight.

-

An aerial view of a 33-megawatt data center in Vernon, California. An aerial view of a 33-megawatt data center in Vernon, California. Is This What an Economic Bubble Looks Like?
AI investment is soaring, but returns remain uncertain.
CA: There’s a lot of talk about the Iran war leading to inflation, leading to the need for higher interest rates. But this doesn’t seem to be an oil story, because the price of oil is steady right now and yet interest rates are continuing to go up. Is this about a broader economic growth story in the United States that is producing increased interest rates?
AT: There are a variety of contending stories about these interest rates. This is one of the things that folks maybe outside the financial markets don’t appreciate. Mortgages are ultimately refinanced through bonds, which are issued by banks—mortgage banks or Fannie Mae and Freddie Mac overwhelmingly. This then becomes part of the pool that sits directly alongside U.S. Treasury debt.
What determines those interest rates, those yields—in other words, the relationship between the price that you pay for the bond and the underlying flow of income you derive from it—is determined by this complex array of factors that provide the stuff of endless conversation about the economy much more than, say, chat about how Apple is doing or Nvidia, which is really the stock market story. The macro story is dominated by the questions you’ve just raised.
There is the possibility that this is to do with particular supply shocks and therefore pressure on prices, which one could generalize to a story about a tendency in the modern economy to supply shortage—which tends to drive prices up, right? It could be, on the other hand, a growth story, an excess of demand story—which would be AI in the American case, with huge volumes of new debt being issued and rapid growth.
Of course, there’s the fiscal conversation. Is the problem ultimately that the American government is issuing too much debt? Then there’s drama of the Federal Reserve and who’s in charge of the Fed and what we think Fed policy is going to be. Because the Fed has a huge say in the development of long-run interest rates in particular. All of those narratives are out there right now.
I think the smart money currently is to say: Yes, there’s structural pressure from price shocks; yes, there is also structural pressure from very large government issuance; but the more likely force driving this right now is some story about the relative robustness of the U.S. economy, which is sustaining a lot of economies in an updraft. We’re not in a deflationary moment by any means.
Then, furthermore, there has been a substantial shift in the market’s assessment of the likely reaction function of the Fed. Last year, the markets were still betting that we would see multiple rate cuts by the Fed to address a slowdown in most of the American economy. Now, after the display of bravery by [Fed chair Kevin] Warsh and the Fed leadership, markets are pricing in to increases in interest rates from the Fed side for the rest of this year. That’s a huge shift.
When you put all of those factors together, some people will say this is really alarming, and this may produce instability as hedge fund strategies unwind, and we’re back to the Treasury market story. But a calmer assessment would simply be: This is exactly what you would expect to see interest rates doing in an economy with 3 percent inflation that seems to be running hot and where all of the taps are on.
This is exactly what fixed-income markets ought to be doing, and mortgages are part of that giant pool. It is the logic of this lock-in effect that generates particular issues and the fat that has been under construction of housing. But it’s not in and of itself a sign of anything disastrous happening here.
CA: Are AI data centers pushing up the cost of capital that could go toward financing mortgages? Is that part of the reason that the housing market is freezing, as you mentioned it?
AT: The way I would think about this is not through a kind of piggy bank of money that has to go either to houses or to AI, and then say AI is somehow crowding out housing. The volume of debt issuance by AI is now large enough to be up there with Treasury issuances in certain categories. So, it’s certainly a big factor. But an awful lot of that is being generated essentially by credit creation within the financial system.
That’s the connection: This boom in finance-leveraged investment in AI is creating a hot economy to which the Fed then responds by raising interest rates.
Within the kind of undulating, quite baggy economy—which isn’t tightly constrained by a pot of money but is this expanding, kind of liquid balloon structure of credit—as the hot bit drags the entire economy forward and the Fed responds, the slower-moving bits are squeezed. That is what we are seeing. The equilibrium interest rate for the housing market would probably be lower than it would be for the AI-driven economy. The Fed is caught between one and the other.
We’re seeing this very severely in the supply side, in the construction of everything other than data centers. Since the end of 2023, data center construction has increased at an annualized rate, adding up what they do per month and multiplying it by 12. We’ve seen a $50 billion increase in spending on data center construction and a $120 billion collapse in the construction of absolutely everything else. That’s exactly what you would expect in this ooze model of the economy, where the bit that’s growing fastest is dragging policy into a higher interest rate level—which the AI sector has to absorb because they’re so obsessed with speed, they have to move forward on this.
Everyone else in every other bit of the construction economy is just going, well, in due course we’ll do that project, but now at 7 percent-plus interest rates is not the moment to do it. So that all gets deferred.
I would put it in that kind of way. It’s more a macro crowding out—and it’s not even direct competition for workers, because the people who build data centers are not the people necessarily that are building housing. But it’s in effect by way of the interest rate, which is being set to suit the AI economy and slow it down but is squeezing the more fragile bits of the economy.
