


The company’s board of directors believes the proposed disposal represents a significant step forward in the continued strategic evolution of EnQuest, crystallizing material value from the firm’s UK upstream portfolio, significantly strengthening its capital structure and completing the repositioning toward Southeast Asia.
EnQuest took these steps to establish Southeast Asia as its primary operating region, where it sees significant opportunities for further high-return, capital-efficient growth, and maintain its established focus on operatorship and highly tangible reserves, deploying its operating capabilities and experienced asset teams to enhance value via a number of measures, including recovery factor improvement and conversion of 2C resources.
In addition, the company believes this divestment and recent acquisitions provide a strengthened platform from which to accelerate further organic growth initiatives in Southeast Asia and capitalize on further inorganic growth opportunities across the region. The remaining EnQuest portfolio on a 2025 net participating interest basis, following completion of the proposed disposal and the acquisitions, is expected to benefit from around 70,000 barrels of oil equivalent per day (boe/d) in the Southeast Asia business, with a unit opex of about $11/boe, a reduction of approximately 57% against its 2025 unit opex of $25/boe, generating a pro forma EBITDA of circa $500 million.
While elaborating that production has grown further via the addition of low-cost Seligi 1b gas volumes in 2026, the firm emphasizes the substantial capital-efficient growth potential, including opportunities to leverage existing infrastructure, adding that its Southeast Asia capital investment is focused on high-return production enhancement activity, with minimal infrastructure investment required.
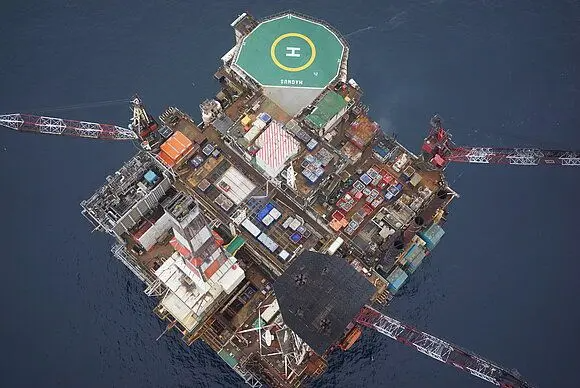
The proposed disposal will involve the sale of all of the issued shares of EnQuest Britain, which through its subsidiaries holds the firm’s UK upstream assets, including Magnus, Kraken, and the Greater Kittiwake Area (operated), Golden Eagle (non-operated), and the undeveloped Bressay field and Bentley discovery.
Additionally, the portfolio entails UK decommissioning and midstream assets, including EnQuest’s operating interest in the Sullom Voe Terminal, the Northern Leg Gas Pipeline, and the Ninian Pipeline system. Employees supporting these operations will transfer to the new owner as a result of the deal.
EnQuest’s UK upstream assets contributed 31,122 boe/d of average net production (92% liquids and 8% gas) for the year ended December 31, 2025, when the portfolio comprised approximately 122 million boe of 2P reserves and 308 million boe of 2C resources.
