


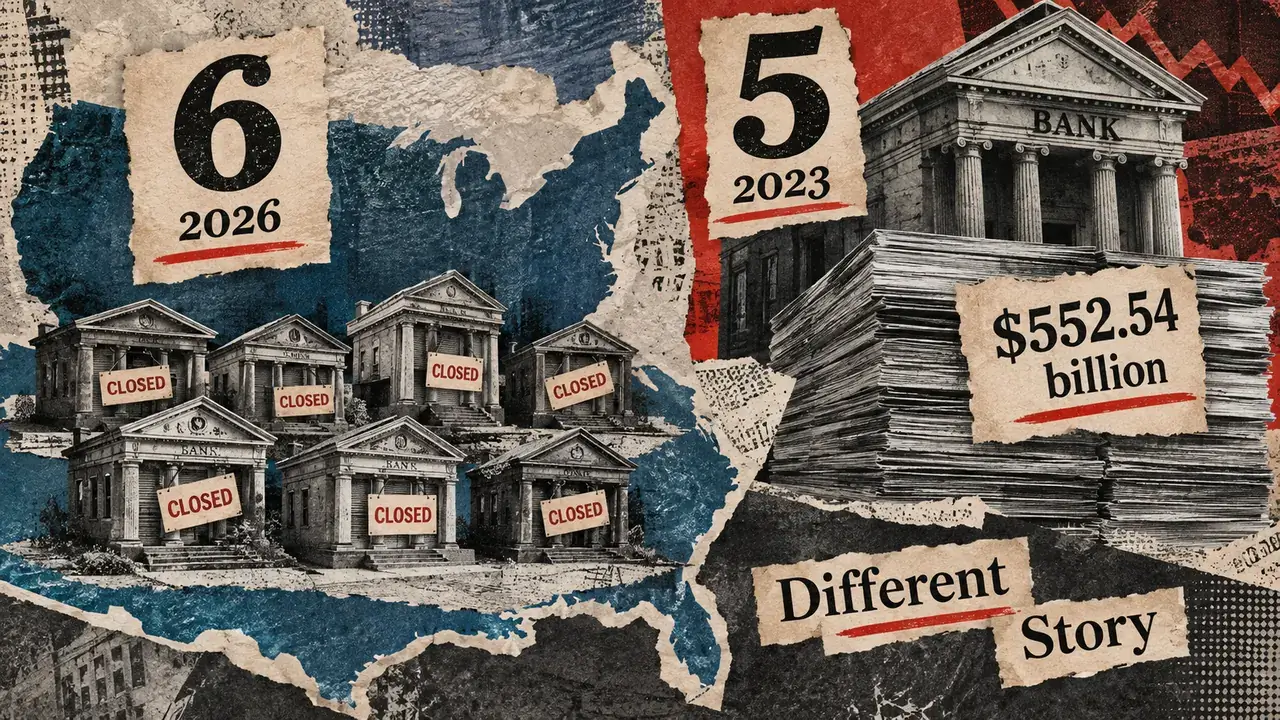
Six US banks have failed in 2026 so far, which is one more than in 2023 and enough to make another banking-crisis headline practically write itself.
But before we start reliving Silicon Valley Bank, it’s worth looking at what those six banks actually held: about $1.43 billion in combined assets, compared with roughly $552.54 billion at the banks that failed in 2023, according to historical numbers from the Federal Deposit Insurance Corporation (FDIC).
Counting each bank as one gives you a perfectly accurate number and a pretty lousy sense of scale. This year’s total includes a lender with $3.73 million in assets, which gets the same vote in the tally as a bank the size of SVB.
Meanwhile, FDIC’s latest industry assessment shows stronger profits and fewer banks on its problem list. That doesn’t mean the six failures were harmless, or that every surviving bank is doing well, but anyone selling a 2023 rerun has some explaining to do.
Nano Banc’s Sept. 25 closure brought the count to six and supplied the largest failure of the year so far. The Irvine, California, lender reported $736 million in assets, and the FDIC estimated a $114 million cost to its Deposit Insurance Fund.
Someone will bear that loss, but a bill attached to one failed bank doesn’t mean the rest of banking is about to follow.
Six is bigger than five (until you look inside)
The FDIC’s annual totals record four failures in 2020, none in 2021 or 2022, five in 2023, and two apiece in 2024 and 2025. Through Sept. 25, this year had beaten every annual count in the 2020s, which sounds much, much worse than it actually is.
Consider Kentland Federal Savings and Loan Association, which the FDIC described as the country’s smallest standalone bank when it closed. Its $3.73 million in assets counts for exactly as much as Silicon Valley Bank in a chart of bank failures, because that chart counts only institutions.
Asking it to measure financial trouble gives a very small bank a very large role.
Sources: FDIC failure announcements and annual summary. The unrounded sum is $1,429.83 million, using numbers from different reporting dates cited around the closures, rather than a single-date balance sheet or an estimate of losses.
The $552.54 billion number for 2023 and this year’s $1.43 billion come from balance sheets with different reporting dates, so we can’t turn them into an exact ratio. Luckily, we don’t need one to see that the amounts belong in very different conversations, even if six is technically more than five.
The FDIC’s problem-bank list adds another issue because it counts banks that are still operating, using their condition measured at a particular date. Banks get onto it when examiners assign one of the two weakest overall ratings for financial, operational, or managerial weaknesses, which is a more specific diagnosis than having an ugly week in the stock market.
The second-quarter assessment put 47 banks on that list as of June 30, down from 54 in March and 60 at the end of 2025. They made up about 1.1% of insured institutions, within the FDIC’s normal 1% to 2% range outside a crisis.
That doesn’t give the industry a certificate of perfect health, because a bank can leave the list by failing just as it can leave by recovering or merging. The failure count adds up closures over the year, while the problem list takes a snapshot of institutions still open, so it’s not mysterious for one to get longer while the other gets shorter.
The dates also prevent us from doing some tempting mental math. Four of this year’s six failures came in July through September, beyond the June snapshot, but subtracting four from 47 won’t tell us how many troubled banks are left.
We don’t know every bank that entered or left the list in between, and the published totals don’t identify them.
Some banks were broken long before the headline
The records behind these closures describe institutions that had been struggling for quite a while. Illinois regulators said Metropolitan Capital had impaired capital and unsafe conditions, while Kansas officials described years of financial trouble at Small Business Bank.
At the Kansas lender, continuing operating losses ate through its capital until it became critically undercapitalized. Capital is the cushion that absorbs losses before creditors have to bear them, and a bank that keeps losing money can burn through that cushion while the rest of the industry has an excellent quarter.
Someone else’s profits don’t refill your bank’s capital, and Kentland reached a similar endpoint, with the Office of the Comptroller of the Currency finding that unsafe practices had depleted its assets and earnings and that there was no reasonable prospect of restoring adequate capital.
Tioga-Franklin had its own FDIC consent order from earlier, covering weaknesses in management and capital planning, as well as liquidity and credit administration. It consented without admitting or denying the charges, so that record tells us supervisors had identified problems, without settling exactly what caused its August failure.
We know less about the full diagnosis at Community Bank and Trust – West Georgia. The state’s closure notice explains the authority to take possession without supplying a detailed financial account, and the FDIC inspector general has a material loss review underway.
Giving it the same cause as the other failures would make the narrative tidier than the evidence allows.
Nano also had a lengthy regulatory history. California Business and Consumer Services Secretary Rohit Chopra described repeated violations and earlier action against mismanagement, while pointing to its large level of uninsured deposits.
Customers with money above the insurance limit have more to lose if a bank fails, which gives them a stronger reason to leave when they doubt it can pay them back.
You can take all of that seriously without treating the six banks as a chain of falling dominoes. The records describe unresolved weaknesses at individual lenders, but don’t establish a common funding shock or show one closure bringing down the next.
Putting them in the same table doesn’t create a financial connection.
The broader numbers don’t support the small-bank-doom argument either. In the FDIC’s second-quarter results, community banks earned 8.2% more than in the preceding quarter, while industry-wide profit reached $90.1 billion.
The regulator described capital and liquidity as strong, leaving plenty of room for a few badly damaged banks in an industry making more money.
The losses are real even when the apocalypse isn’t
None of this makes a failed bank a non-event for the people caught in it.
Nano’s estimated $114 million insurance-fund cost is a real financial consequence, even though Sunwest Bank agreed to take over substantially all its deposits and buy about $476 million of its assets.
The FDIC retained the rest for disposal and said customers could keep using checks and cards through the closure weekend.
Those customers could keep paying their bills while the receivership faced a loss, because access to deposits and the final cost of resolving a bank aren’t the same thing.
The FDIC’s estimate can move as it sells retained assets, and the six banks’ combined $1.43 billion in assets shouldn’t be treated as money that vanished. Loans can still be repaid, and securities can still be sold when their former owner has failed.
Tioga-Franklin’s buyer assumed all deposits, while the West Georgia transaction transferred substantially all insured deposits, excluding certain brokered accounts.
Georgia officials said customers above the insurance limit would receive notices explaining their rights as uninsured depositors, which is a pretty different experience from being told your account now has another bank’s name on it.
CryptoSlate’s coverage of the year’s first bank failure examined broader banking risks, but the road from a failed lender to crypto still needs spelling out. Whose money was at the bank, and what could they no longer do when it closed?
In 2023, Circle had $3.3 billion of USDC reserves at Silicon Valley Bank, giving stablecoin holders a direct reason to worry about access to part of their tokens’ backing. The Federal Reserve’s analysis of that failure follows that connection from bank distress into stablecoins.
This year’s tally doesn’t provide an equivalent connection on its own. Disclosed crypto deposits at a failed lender, or the loss of banking services needed to process customer payments, would give us something concrete to examine.
Another tick in the failure column can’t tell us whose reserves are trapped or whose business has lost access to cash.
There are good reasons to keep watching the banks, including whether withdrawals spread across institutions and whether lenders have more trouble obtaining funding. The assets on the problem-bank list deserve attention too, because a shorter list can still contain more money at risk.
None of those possibilities gets answered by comparing six with five.
The case for another 2023 has to explain how trouble is spreading through the banks that are still open. Until the evidence shows that, six failed lenders tell us that six lenders couldn’t keep going, and turning that into a verdict on the whole system asks a headcount to do a balance sheet’s job.
